
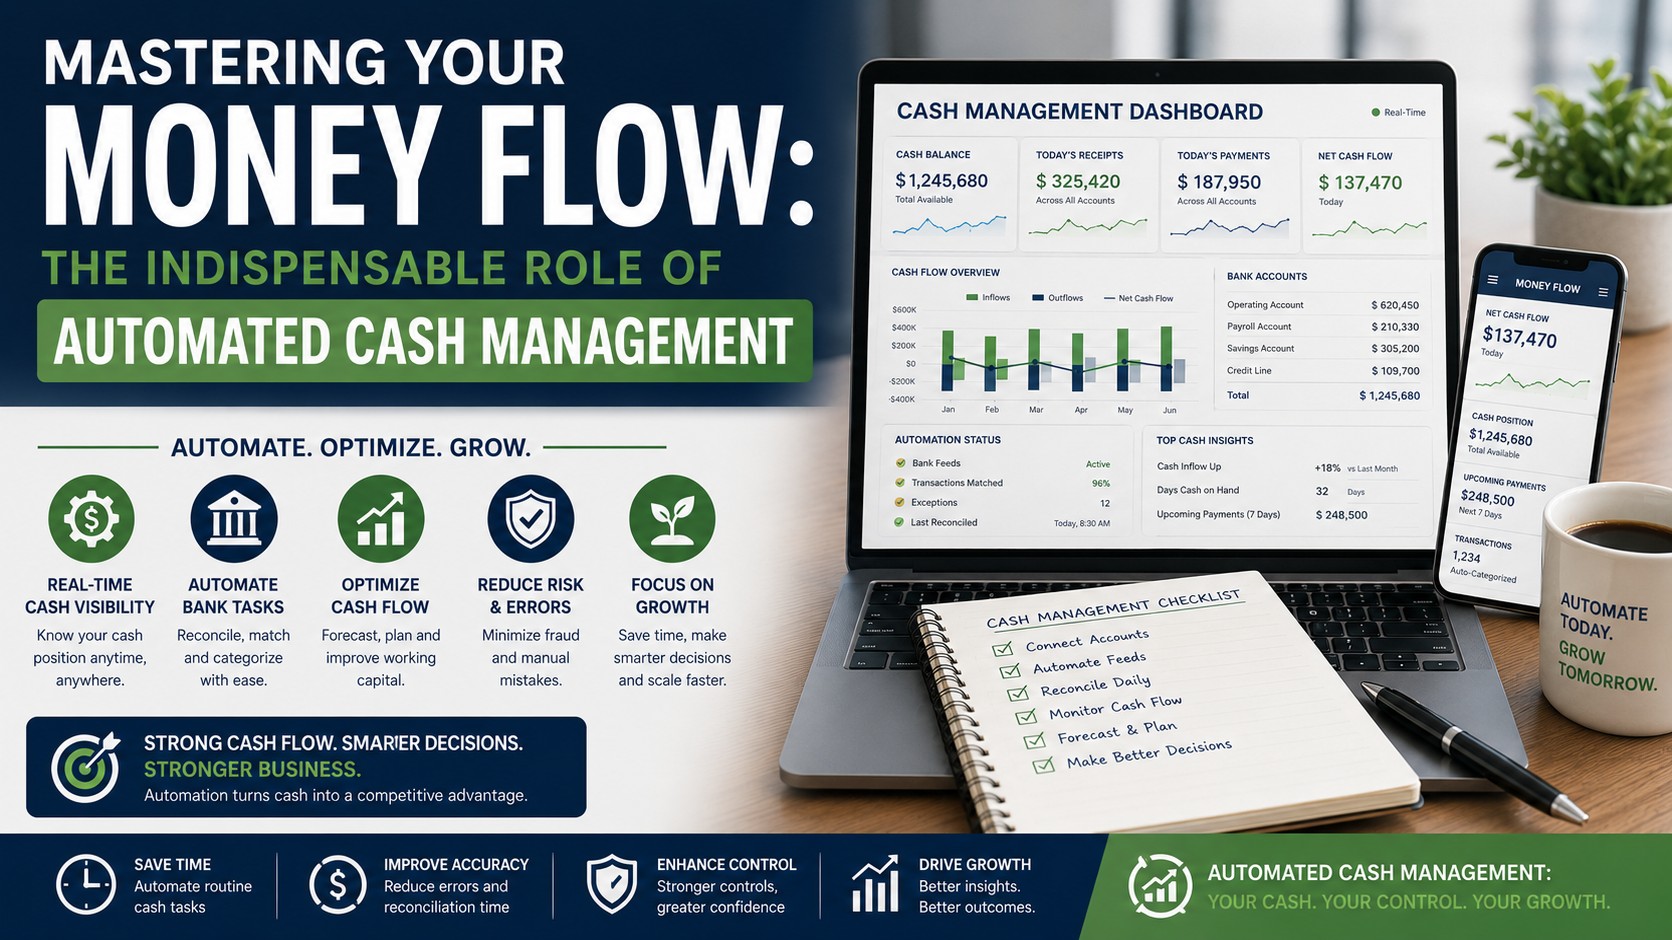

Automated cash flow management begins with timing
A business can earn a profit and still struggle to pay wages, suppliers or loan instalments. Sales may be booked before customers pay, inventory may absorb funds and equipment purchases may fall due before borrowing is disbursed. Cash management brings these timings into one view. Automation can reduce repeated calculations and preparation work, but it must operate on complete, reviewed information.
For an Indian MSME, a practical process starts with confirmed available cash, expected collections and scheduled payments. Add the operating cycle, debt obligations and planned investments. The objective is to identify a shortage early enough to respond. A dashboard becomes valuable when each important figure has a source, an owner and an expected date.
Match cash flow automation to the task
Distinguish operating cash management from the projected cash flow in a bank-loan report. A rolling operating forecast needs current collection and payment assumptions. A project report connects forecast receipts and payments with investment and debt repayment. Finxora’s project-report page documents projected statements and repayment workings; assess live feeds, reminders or payment execution separately before expecting those capabilities.
For the borrowing proposal, review the cash flow projection for a bank loan and the project report software page.
Separate three different financial views
The profit and loss account measures income and expenses under the applicable accounting basis. A historical cash-flow statement explains cash movements over a completed period. A forward cash forecast estimates when money will enter and leave the business. These views support one another, but they should not be substituted for each other.
A bank-loan project report may contain annual projected cash flows, while the accounts team needs a weekly view of collections and payment commitments. The annual projection supports funding and repayment assessment. The weekly forecast supports immediate decisions about payment dates and available balances. Maintain a reconciliation between the two horizons without implying that an annual report confirms today's bank position.
Establish the opening cash position
Start from reconciled bank and cash balances. Identify restricted funds, uncleared transactions, committed payments and balances that cannot be transferred freely. Separate cash actually available from an unused borrowing limit. A sanction letter and a drawable facility are different pieces of evidence; availability may depend on conditions or drawing-power calculations.
Record the date and time of the starting position. If information is updated only once a week, label it accordingly. Do not describe a manually refreshed file as real-time cash visibility. The update frequency should match the decisions being made, and the team should know when an important payment or receipt has occurred since the last refresh.
Forecast receipts from individual collection evidence
Begin with outstanding customer invoices, expected receipt dates and collection responsibility. Ageing helps identify risk, but it does not prove when payment will arrive. Consider disputes, customer commitments, recent payment behaviour and concentration in a few large accounts. Keep confirmed receipts separate from optimistic estimates so that a single uncertain collection does not support several promised payments.
For future sales, connect expected receipts to the sales forecast and customer credit terms. Avoid counting both an outstanding invoice and the same amount again through a general sales collection assumption. Separate advances, deposits and refunds from ordinary customer collections. A clear classification makes the forecast easier to reconcile with actual bank movements later.
Schedule payments by obligation and date
Build a payment calendar covering suppliers, payroll, rent, utilities, taxes, interest and principal. Add planned equipment purchases and owner withdrawals where relevant. Identify which amounts are contractually due, which are estimates and which can be rescheduled through an agreed commercial discussion. Do not assume a payment can be delayed simply because the forecast would otherwise show a deficit.
- Keep approved supplier invoices distinct from unapproved purchase estimates.
- Separate loan principal from interest for reconciliation.
- Show statutory payments on their applicable dates.
- Record one-off capital expenditure outside routine operating costs.
- Assign responsibility for confirming uncertain amounts.
Use consistent treatment for taxes in receipts and payments. A forecast built from tax-inclusive customer collections and tax-exclusive supplier payments can overstate available cash. The same problem arises when scheduled deductions or recoveries are omitted. Write the basis of preparation alongside the forecast rather than leaving the treatment implicit.
Automate calculations before automating decisions
Repeated summation, date grouping and balance roll-forwards are suitable candidates for automation. The core relationship is opening available cash plus receipts less payments equals closing available cash. Carry the closing balance into the next period and flag any shortfall. The calculation should remain easy to inspect even when data arrives through several sources.
Automation does not establish that a customer will pay or that a supplier invoice is valid. Maintain approval controls for payments and review unusual entries. Where a business evaluates bank feeds, accounting connections or payment tools, verify those capabilities with the vendor and test their actual behaviour. They should not be assumed merely because a product offers a cash-flow report.
Use scenarios to expose timing risk
Prepare a base forecast and separate downside workings. Test slower collections, higher input costs, lower sales or delayed borrowing. Change the relevant drivers rather than reducing every receipt by the same percentage without explanation. The scenario should reveal which week or month becomes difficult and the amount of funding required at that point.
Suppose opening available cash is Rs 4 lakh, expected receipts are Rs 8 lakh and scheduled payments are Rs 10 lakh. The base closing balance is Rs 2 lakh. If Rs 3 lakh of collections moves into the next period, that period instead shows a Rs 1 lakh shortage. An annual profit figure would not reveal the timing problem. The team needs a response before the payment date.
Choose a response that matches the cause
A temporary collection delay may call for customer follow-up, revised payment sequencing or an appropriate short-term facility. A persistent operating deficit requires examination of pricing, costs, credit policy and the business model. Repeated borrowing should not conceal losses that the underlying operation cannot fund. Explain the cause before selecting the financial response.
Record proposed actions with an owner, expected amount and deadline. Keep unconfirmed actions outside the committed forecast until evidence supports them. If the plan depends on a customer promise, promoter contribution or lender disbursement, show that dependency clearly. This prevents a revised spreadsheet from creating false confidence without changing the actual cash position.
Connect cash planning with financial reporting
Finxora's project report software includes projected cash flow alongside financial statements, repayment schedules and DSCR workings. Its CMA report software includes cash-flow and fund-flow sections for bank appraisal. These capabilities support financial preparation; they do not establish live bank synchronisation, payment execution or automated customer collection.
Use the reporting model to explain funding requirements and repayment assumptions, then maintain the operational collection and payment process appropriate to the business. Review sample reports to understand the exported presentation. Ask a vendor to demonstrate any additional operational capability before including it in a purchasing decision or relying on it for daily cash control.
Review actual results against the forecast
At each refresh, replace elapsed estimates with actual receipts and payments. Classify differences as timing changes, amount changes or missing items. Investigate repeated optimism in collection dates and overlooked expenses. Preserve the earlier forecast so that the team can learn from the variance instead of rewriting the history.
A reliable cash-management process combines consistent calculations with accountable follow-up. Automation helps when it reduces repetitive work and makes exceptions visible. The finance team still needs to validate inputs, confirm commitments and act on shortages. Regular reconciliation and realistic timing make the forecast a practical basis for decisions.